
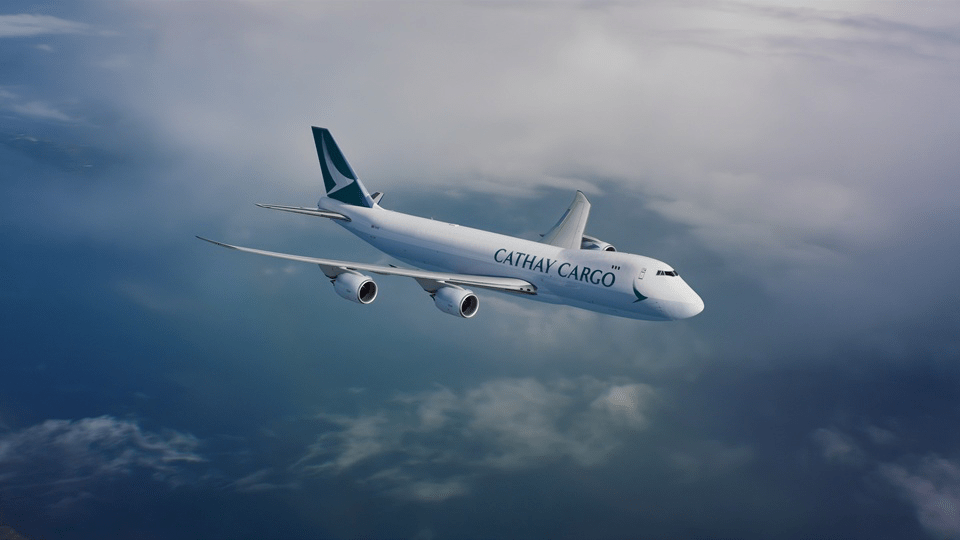
Cathay Cargo recorded another month of strong volume growth in August, with tonnage increasing 8.6% year on year despite disruption to the China-Europe e-commerce market following the European Union’s introduction of a new €3 customs duty on low-value imports.
The Hong Kong-based carrier transported 151,904 tonnes of cargo during the month, taking year-to-date growth to 8.2%. Revenue freight tonne-kilometres (RFTKs), however, increased at a more modest rate of 3.1%, indicating that the growth in tonnage was accompanied by a shorter average transportation distance.
Available freight tonne-kilometres (AFTKs) increased 1.4% in August, while Cathay Cargo’s load factor improved by 0.9 percentage points to 57.4%.
Semiconductor and Pharmaceutical Demand Supports Growth
Cathay Chief Customer and Commercial Officer Lavinia Lau said cargo demand remained healthy across the carrier’s key markets.
She highlighted strong demand for Cathay Expert, particularly for semiconductor shipments within Asia, while Cathay Pharma recorded notable growth on traffic from Europe and the Chinese Mainland.
Cathay Priority also continued to perform strongly as shippers moved to replenish inventories ahead of the traditional year-end air cargo peak.
“Cargo tonnage in August was supported by healthy demand across our key markets,” Lau said, adding that demand was expected to remain firm as the industry moves into the peak season.
The carrier expects high-tech product launches and rising seasonal demand to provide further support in the coming months.
EU Duty Reshapes Low-Value E-Commerce Flows
Cathay’s growth comes against a changing regulatory backdrop for cross-border e-commerce.
From 1 July 2026, the EU ended its previous customs duty exemption for imports valued at €150 or less and introduced a temporary €3 customs duty. Importantly, the duty applies per item category within a low-value consignment rather than simply as a flat fee on every package. The measure is scheduled to remain in place until 1 July 2028, when it is intended to be replaced by normal tariff arrangements under the EU’s customs reform.
The change has already affected China-Europe air cargo flows. WorldACD reported that July tonnages from Hong Kong to Europe fell 19% from June and were 24% below the level recorded in July 2025. Mainland China-Europe volumes declined 3% month on month and 6% year on year in July.
Against that backdrop, Cathay’s continued overall tonnage growth points to resilient demand across other markets, particularly within Asia.
HKIA Cargo Volumes Decline
The broader Hong Kong air cargo market presented a more mixed picture in August.
Hong Kong International Airport handled around 428,000 tonnes of cargo during the month, a 1.2% decline compared with August 2025, although volumes remained 2.7% higher year to date. The airport had also recorded a decline in July following the implementation of the EU’s new low-value import rules.
According to figures cited by the Airport Authority Hong Kong, exports fell 8.8% year on year in August, while transshipments increased 18.2% and imports rose 3.6%. Southeast Asia and the Chinese Mainland remained relatively resilient, helping offset weaker traffic associated with Europe and the Middle East.
The contrasting performance highlights the uneven impact of changing trade rules across the region. While Europe-linked e-commerce flows have come under pressure, intra-Asian demand and other cargo segments continue to provide support for Hong Kong’s airfreight market.
Peak-Season Demand in Focus
Cathay’s August results suggest that the carrier is entering the traditional air cargo peak season with solid underlying demand.
The performance of semiconductor, pharmaceutical and inventory-replenishment shipments is particularly significant as global supply chains prepare for the final months of the year. At the same time, the impact of Europe’s new low-value import regime is likely to remain an important factor for carriers serving the China-Europe e-commerce market.
For Cathay Cargo, the immediate outlook remains centred on sustained demand from high-tech products and seasonal inventory movements, while market dynamics across Europe and Asia continue to evolve.