
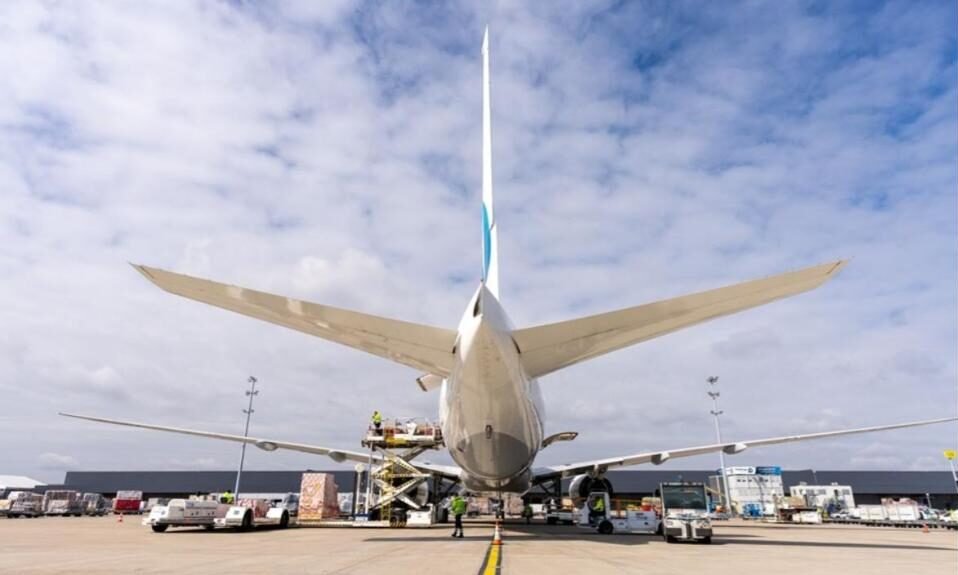
Technology and manufacturing are supporting freight demand, but surging jet fuel prices, aircraft shortages and higher operating expenses are putting pressure on carriers’ profitability.
Global air cargo demand is showing renewed strength, supported by economic activity and robust trade flows in technology and manufacturing. However, rising fuel prices and mounting aviation costs are creating a challenging environment for airlines and freight operators seeking to convert higher volumes into sustainable profits.
Recent market data point to firm freight rates as the industry enters the peak shipping season. The combination of resilient demand, constrained aircraft availability and escalating fuel expenses is reshaping the economics of air cargo, putting greater emphasis on capacity management, pricing strategies and operational efficiency.
Demand growth meets capacity constraints
The International Air Transport Association (IATA) reported that global air cargo demand, measured in cargo tonne-kilometres, increased by 4.4% year-on-year in August 2026. International cargo demand grew by 5.3%, with North American carriers recording a particularly strong performance.
At the same time, industry-wide available cargo capacity declined by 0.1% year-on-year in August. The tighter balance between demand and capacity helped lift the global cargo load factor by two percentage points to 46%, according to IATA.
Manufacturing output and new export orders continued to expand, supporting freight flows across major trade lanes. Technology-related shipments have also been an important source of demand, particularly on routes connecting Asian manufacturing centres with North America and Europe.
Fuel costs put pressure on profitability
The strength in cargo demand comes as airlines face a sharp increase in fuel expenses. IATA’s June 2026 industry outlook projected that global airline fuel costs would rise by nearly 40% during the year, reaching US$350 billion. It also forecast that the industry’s overall net profit would fall to US$23 billion, with a net margin of around 2%, reflecting the impact of higher fuel prices and geopolitical disruption.
Freight rates have risen in response to changing market conditions, but higher prices do not automatically translate into improved margins. Carriers must also contend with aircraft leasing costs, maintenance expenses, labour and the challenge of securing additional capacity when demand peaks.
Data from TAC Index showed that its global Baltic Air Freight Index had risen 21.7% year-on-year by September 28. The increase accelerated in early October, with the index climbing a further 5% in the week to October 5. TAC also reported that jet fuel prices had more than doubled year-on-year by early October, intensifying pressure on cargo operators.
Peak-season outlook remains mixed
The latest market developments underline the importance of balancing capacity against volatile demand and operating costs. WorldACD reported that global chargeable air cargo weight rose 2% week-on-week during October 12–18, led by a 9% rebound in shipments from Asia-Pacific as factories resumed activity following China’s Golden Week holiday period. Global air cargo rates also increased by 4% over the week.
For airlines, freight forwarders and shippers, the coming months will depend on how demand develops across major trade lanes, whether fuel prices remain elevated and how much additional capacity carriers can deploy.
The market’s immediate challenge is therefore twofold: meeting demand for time-sensitive freight while protecting profitability against a higher cost base. Strong cargo volumes offer opportunities, but the ability to manage fuel exposure, fleet utilisation and capacity efficiently will be critical to sustaining financial performance.