
Global air cargo demand is expected to increase by 2.5% to 3% over the next 12 months, but escalating fuel costs are likely to put further pressure on airline profitability, according to air cargo data and consultancy firm Rotate.
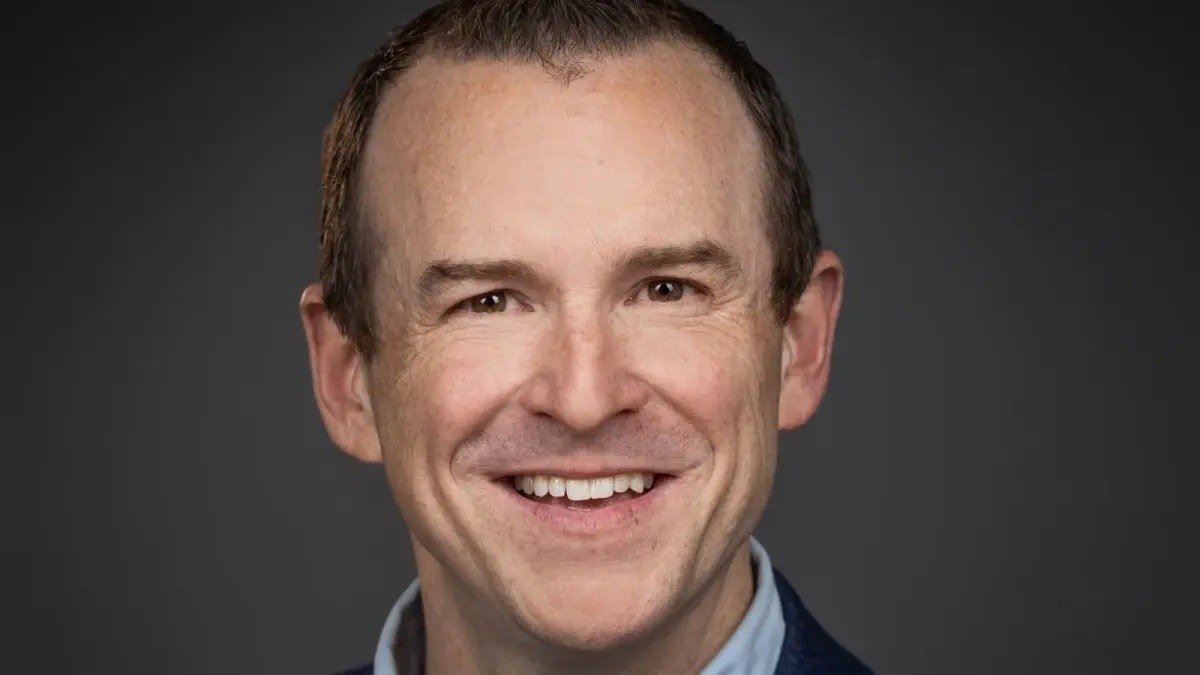
Speaking at the International Air Cargo Association’s (TIACA) Air Cargo Forum in Miami on 27 October, Ryan Keyrouse, CEO and co-founder of Rotate, said the industry was approaching a more balanced supply-and-demand environment, although significant differences would remain across individual trade lanes.
Rotate forecasts air cargo capacity growth of approximately 2% over the same period, suggesting that supply expansion will broadly track demand.
Related Post
Keyrouse said the industry was experiencing a strong period of growth despite mounting concerns over fuel prices and operating expenses.
The outlook reflects a market that continues to benefit from robust e-commerce activity and increasing shipments linked to artificial intelligence (AI) infrastructure, even as airlines face tighter operating margins.
E-commerce and AI drive more than two-thirds of cargo growth
E-commerce and AI-related shipments have emerged as the principal drivers of recent air cargo expansion.
According to Rotate’s analysis, e-commerce-related commodities accounted for 36% of the increase in cargo tonnage between January and July 2024 and the corresponding period in 2026.
Cloud computing, computers and computer components, and semiconductors contributed a further 33% of the growth.
Together, these categories represented approximately 69% of the additional cargo tonnage, highlighting the increasing concentration of global air freight demand around digital commerce and technology-related supply chains.
However, both segments are experiencing changing market conditions.
In Europe, the introduction of additional duties on low-value e-commerce shipments has affected parcel volumes. Keyrouse noted that other commodity categories had not yet fully compensated for the resulting decline.
Rotate’s industry sentiment survey indicated that most respondents expected e-commerce volumes to recover, although a meaningful rebound was not anticipated during the first six months.
Further regulatory changes and additional charges could influence the pace of recovery.
AI-related cargo growth begins to moderate
AI infrastructure investment continues to generate substantial demand for air freight, particularly for semiconductors, computing equipment and associated technology components.
However, Rotate has identified signs that the exceptionally rapid growth in AI-related shipments is beginning to moderate.
Keyrouse said investment in AI infrastructure remained closely correlated with air cargo tonnage, with spending on computing capacity providing an important indicator of future freight demand.
Nevertheless, energy availability, regulatory considerations and infrastructure constraints could influence how quickly investment translates into additional cargo movements.
Industry survey respondents remained optimistic about the long-term outlook for AI-related shipments but generally expected a more moderate rate of expansion.
The geographical distribution of this demand is also changing. India, Malaysia and Thailand are emerging as increasingly important data centre markets, while the United Arab Emirates is attracting investment in AI and digital infrastructure.
This geographical expansion could create new opportunities for airlines and logistics providers serving technology-intensive trade corridors.
China Plus One strategy reshapes global trade lanes
Changes in international trade patterns and tariff policies are continuing to influence the movement of air cargo.
Manufacturers are increasingly diversifying production beyond China, adopting China Plus One strategies to reduce supply chain concentration and strengthen operational resilience.
This shift is gradually changing the composition and direction of international freight flows.
Keyrouse highlighted the declining movement of cargo from China to the United States alongside increasing shipments from Southeast Asian manufacturing centres to the US market.
For airlines, these developments have important implications for network planning, capacity allocation and long-term commercial strategies.
As production becomes more geographically diversified, carriers will need to adapt their networks to accommodate changing export origins and evolving customer requirements.
Rising fuel costs tighten freighter operating margins
Despite strong cargo demand, higher fuel prices are creating significant financial challenges for airlines.
Rotate’s modelling indicates that increasing fuel expenditure is narrowing the gap between freighter operating revenues and costs, making profitability increasingly dependent on individual route economics.
The pressure is particularly evident on the transpacific market, where airlines often depend on stronger cargo revenues in one direction to offset weaker returns on return flights.
Keyrouse warned that the narrowing margins were making network planning more complicated, requiring airlines to evaluate both directions of a route rather than focusing solely on the performance of stronger outbound sectors.
The situation highlights a growing challenge for freighter operators: maintaining profitability in a market where cargo volumes remain healthy but operating expenses are rising faster than revenue in certain corridors.
The economics of individual trade lanes are therefore becoming increasingly important in determining aircraft deployment, capacity decisions and commercial performance.
Peak-season expectations remain positive
Despite cost pressures and changing demand patterns, industry sentiment towards the 2026 peak season remained broadly optimistic.
According to Rotate’s survey, approximately 70% of respondents expected this year’s peak season to perform at least as well as, or better than, the corresponding period in 2025.
The survey also indicated that 70% of participants anticipated air cargo demand growth of between 2% and 4% over the next 12 months, broadly supporting Rotate’s overall forecast.
However, a more balanced global supply-and-demand environment does not necessarily mean that capacity will be evenly distributed across all markets.
Individual trade lanes will continue to experience differences in demand, available aircraft capacity and operating economics.
Keyrouse said airlines and logistics companies would increasingly compete to identify commercially attractive opportunities across these markets.
A more balanced market, but greater operational complexity
Rotate’s outlook points towards a period of more moderate global air cargo growth, with demand and capacity expansion moving closer together.
However, the underlying market remains influenced by several structural changes, including the expansion of e-commerce, AI infrastructure investment, manufacturing diversification and persistent fuel cost volatility.
For airlines, the challenge will be to convert demand growth into sustainable profitability while managing increasingly complex international networks.
The outlook reinforces the importance of flexible capacity planning, accurate market intelligence and disciplined route-level cost management as the global air cargo industry enters its next phase of expansion.