
Asia’s air cargo market is entering the traditional fourth-quarter peak with capacity conditions expected to vary significantly by origin, destination and commodity, according to C.H. Robinson’s October freight market update.
The freight forwarder said late September was characterised by quarter-end activity and cargo brought forward ahead of China’s National Day and Golden Week holiday. With factories temporarily closing from October 1 to 7, the market is expected to experience a short-term lull before export volumes begin returning from mid-October. The speed and strength of that recovery will be a key indicator for air cargo capacity through the remainder of the fourth quarter.
Technology-related shipments remain one of the strongest sources of demand, particularly on transpacific routes. Servers, semiconductor equipment, data-centre components and other high-value electronics continue to generate significant volumes, while new consumer-device launches are adding further time-sensitive freight.
Related Post
General cargo is expected to build more gradually as manufacturers and retailers replenish inventories ahead of early Black Friday promotions, Cyber Monday and the year-end shopping period. At the same time, e-commerce is playing a smaller role in the 2026 peak season. Changes to tariff rules for low-value imports have reduced some e-commerce flows into the US, while Asia-Pacific-to-Europe volumes remain below last year’s levels, particularly on e-commerce-heavy lanes.
Technology cargo drives transpacific demand
The concentration of demand in technology and other time-sensitive commodities is creating a more selective peak-season market rather than broad-based pressure across all cargo categories.
C.H. Robinson expects Asia-Europe demand to remain less broadly constrained than the transpacific market, although individual technology-heavy origins could experience tighter capacity. Technology, semiconductors, AI infrastructure, industrial manufacturing and selected healthcare cargo are providing steady demand, while weaker e-commerce volumes are moderating overall growth.
China, Southeast Asia and India are therefore likely to experience different market conditions. Cargo mix, aircraft type, gateway performance and airline schedules can all influence the amount of capacity actually available to shippers at individual origins.
Freighter allocation could affect other markets
A stronger concentration of demand on US-bound routes could also influence capacity elsewhere.
Airlines typically adjust aircraft deployment, schedules and commercial allocations in response to changes in booking activity. If additional freighter capacity is directed towards the transpacific market following Golden Week, some Asia-Europe origins could face tighter options even without a significant increase in European import demand.
That makes the post-Golden Week period particularly important. A rapid return of export cargo could keep preferred departures heavily booked and encourage carriers to maintain or increase capacity on the strongest-performing lanes. A slower recovery, by contrast, could allow capacity conditions to normalise more quickly.
C.H. Robinson’s September outlook had already identified earlier cut-offs and fewer workable flight options as potential initial signs of tightening, rather than an immediate broad-based increase in rates.
Europe-North America market presents a different picture
The Europe-North America market enters October with a different supply-demand balance from Asia.
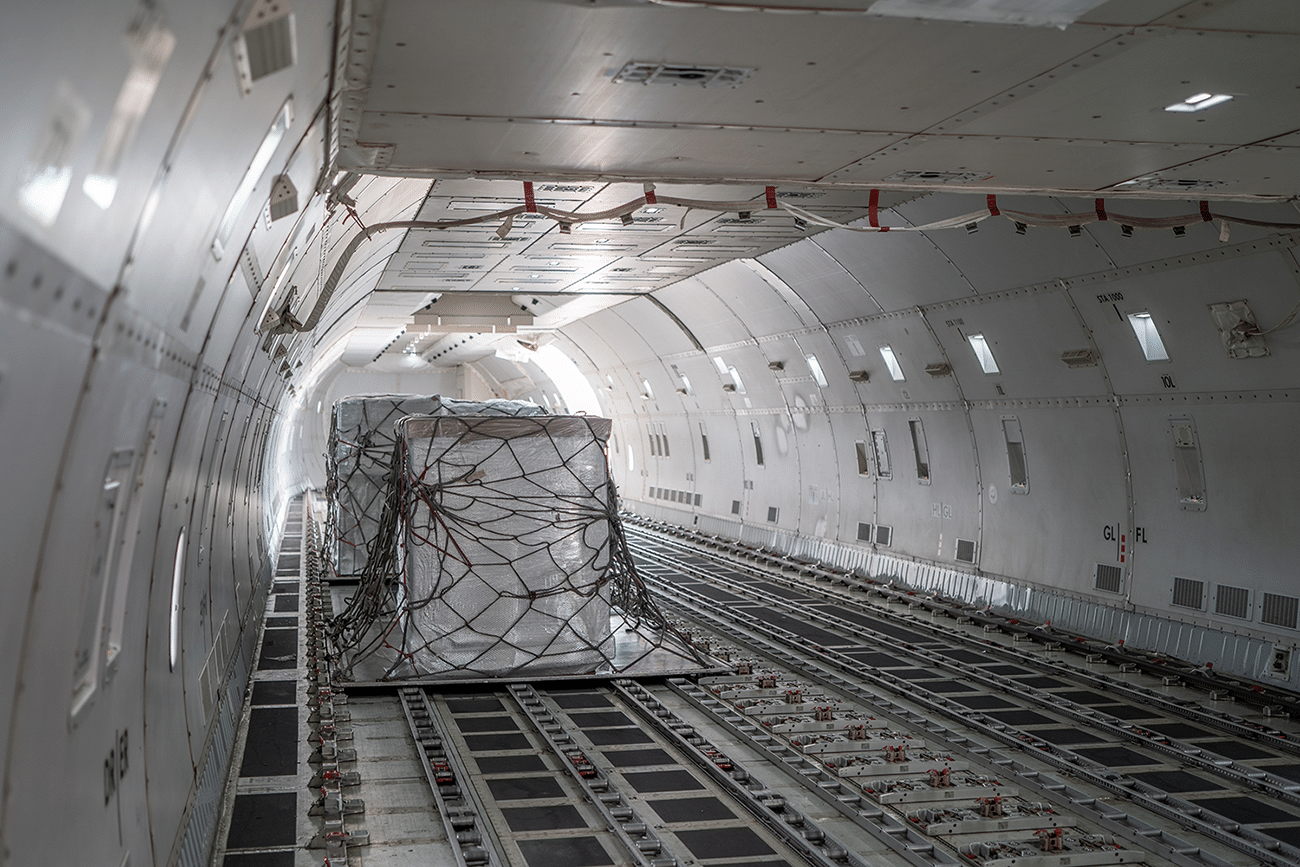
Standard cargo can generally access passenger belly capacity, but capacity is less interchangeable for shipments that require dedicated freighter equipment or specialised handling. Oversized and heavy freight, pharmaceuticals, temperature-controlled shipments and project cargo can face fewer routing options and require greater lead time.
The distinction is important for shippers. Available transatlantic capacity does not necessarily mean that every commodity can move with the same flexibility. Aircraft type, handling requirements, dimensions and temperature-control needs can all narrow the range of suitable departures.
Elevated fuel costs also remain an important consideration for airline and cargo economics as carriers enter the final quarter.
Golden Week creates a critical October test
The immediate market disruption from China’s Golden Week is expected to be temporary, but the post-holiday recovery could determine how the air cargo market develops through the rest of Q4.
A stronger-than-expected return of manufacturing and export activity could quickly fill preferred departures, particularly on technology-heavy transpacific routes. If demand returns more gradually, airlines may have greater flexibility to rebalance schedules and capacity.
For shippers, the October market therefore calls for a more granular approach to capacity planning. Rather than assessing the market purely at regional level, companies will need to consider the specific origin, commodity, aircraft type and destination involved in each shipment.
The latest outlook points to a peak season defined less by an across-the-board capacity shortage than by selective pressure where strong technology demand, specialised cargo requirements and limited freighter capacity intersect.